
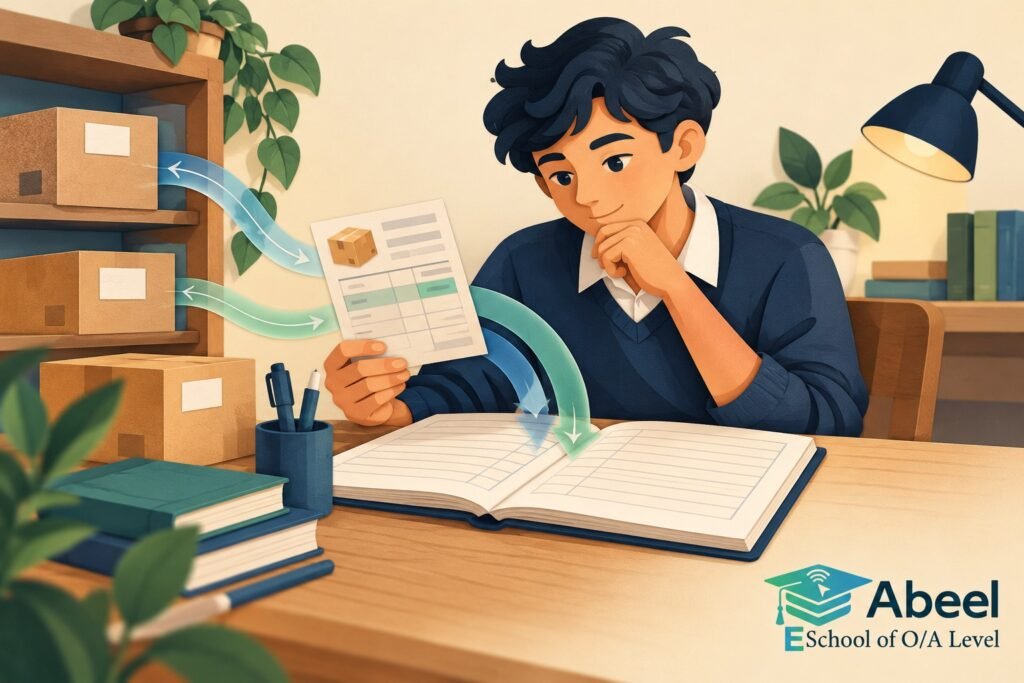
A changed inventory figure can affect more than one part of an accounting answer. Ask the learner where the figure enters the calculation and which later statement uses it. Tracing that path distinguishes a valuation decision from an arithmetic slip after the value has been chosen.
For qualification-wide planning, use the O Level revision framework or, for AS and A2 students, the A Levels in Pakistan study plan. The exercise below is an original illustration, not an official examination question. Match any assessed preparation to the current subject syllabus and paper.
Locate where the inventory value enters cost of sales
Ask the student to identify what closing inventory represents in the question. It is not the same as sales or purchases during the period. In a straightforward trading calculation, goods remaining at the end reduce the cost attributed to goods sold. That relationship explains why changing closing inventory affects cost of sales in the opposite direction.
Keep the complete question beside the attempt. The teacher needs to see the opening inventory, purchases, closing figure and any valuation information. A final gross-profit number alone gives little evidence about where a misunderstanding began. The learner might have used the right formula with a wrong valuation, or valued correctly but placed the figure on the wrong side of the calculation.
Ask for an ordinary explanation before insisting on technical phrasing. The student might say that goods still held were not all sold in the current period. The teacher can then refine that statement and connect it to the cost-of-sales calculation. A formula becomes easier to check when its terms have meaning rather than acting as a sequence of signs to remember.
Trace the same change into profit and the closing position
Imagine an invented trading exercise with opening inventory of 4,000, purchases of 18,000 and closing inventory of 5,000. Ignoring other purchase-related adjustments, cost of sales is 4,000 + 18,000 − 5,000 = 17,000. If sales are 30,000, gross profit is 13,000. Each figure has a clear role in the chain.
Now suppose closing inventory was mistakenly entered as 5,800. Cost of sales becomes 16,200 and gross profit 13,800. The 800 overstatement of inventory understates cost of sales by 800 and overstates gross profit by 800. Ask the student to describe both links rather than learn only that inventory changes profit.
The Okara inventory valuation practice guide develops the calculation and the valuation decision behind it. Use it to discuss the student's reasoning, then ask a teacher to select a fresh question. One correctly copied chain does not establish that the learner can trace a different adjustment independently.
Separate the valuation decision from the arithmetic
Closing inventory may require a comparison between cost and net realisable value under the stated exercise. The student needs to establish the appropriate value before inserting it into cost of sales. If that first decision is wrong, later arithmetic may be internally consistent while the final figures remain unsuitable.
Ask what the net realisable value includes. In a simple example, estimated selling proceeds may need to be reduced by relevant costs of completion and sale. The full expected selling price is therefore not automatically the amount used in the comparison. A teacher can help the learner identify the supplied deductions rather than treating every market-related figure as interchangeable.
Also distinguish quantity from valuation. Counting the correct number of units does not establish the correct amount per unit, and selecting an appropriate amount per unit does not prove the units were counted correctly. A review should identify which part of the inventory figure needs attention. The next task should match that uncertainty instead of repeating every stage unnecessarily.
Ask which other statement uses the same figure
Closing inventory is also an asset in the statement of financial position under the simple scenario. If the figure is overstated, the asset total is overstated. With other items unchanged, the resulting profit effect also changes equity. The learner should connect the income-statement consequence with the position-statement consequence rather than treating them as unrelated corrections.
A useful teacher question is where the same amount appears elsewhere in the answer. Ask the student to point to it and explain whether it needs the same correction or a different linked calculation. This checks the structure of the accounts, not just subtraction. A complete correction should restore a consistent set of figures across the answer.
The Dera Ghazi Khan trial-balance guide provides a related lesson about the limits of an apparently successful check. Matching totals or a plausible gross-profit percentage does not prove the underlying valuation is correct. Each check has a purpose, and the teacher should explain what evidence it actually supplies.
Follow the amount across a period boundary
The closing inventory of one period normally becomes the opening inventory of the next in these exercises. An error can therefore affect the following period differently. If an overstated closing figure becomes an overstated opening figure next year, that higher opening cost tends to reduce next year's profit, assuming the other relevant figures are correct.
This does not make the original error harmless. Each period's reported result can be wrong, and users may rely on those separate results. Ask the learner to state which period is being discussed before describing an overstatement or understatement. A memorised answer about closing inventory can be reversed incorrectly when the question is actually about opening inventory.
The Kasur period-boundaries guide offers a connected example of why opening and closing amounts receive different treatment. The adjustment methods differ, but both topics require the student to identify where a figure belongs in time before choosing the sign or the final interpretation.
Make feedback name the missing connection
If the learner corrects cost of sales but leaves gross profit unchanged, record that specific observation. The issue is not simply inventory weak. The student needs to trace the calculation into its next dependent figure. A teacher can ask for a small before-and-after comparison rather than immediately assigning another full set of financial statements.
If the valuation itself was wrong, keep that separate from a later arithmetic error. The student may need one task comparing cost with net realisable value and another task following an already supplied inventory change through profit. Combining every difficulty into one large exercise can make it harder to see which skill improved.
Use the independent-attempt approach to record prompts. A teacher asking which figure changes next is useful support, but a fresh attempt is needed to see whether the learner now makes the connection unaided. Keep the original page, correction and later attempt together so the review refers to visible evidence.
Fit the next task into the actual course
Confirm the syllabus code, examination year and current school topic before selecting more questions. Use the Pakistan O Level revision plan for wider scheduling, or the Pakistan A Level study guide where appropriate. A teacher should explain why the exercise fits the student's route and what prior knowledge it assumes.
Agree on a manageable follow-up that can be reviewed. One fresh valuation and one linked profit explanation may provide better evidence than many uninspected totals. If the student understands the chain but struggles with the language of overstatement, practise that wording directly. The lesson plan should respond to the observed decision rather than a fixed quantity of pages.
Try a short independent check
Holding other figures constant, increasing closing inventory by 150 reduces cost of sales by 150 and increases gross profit by 150. The closing inventory asset also increases by 150. Ask the learner to show the cost-of-sales relationship rather than memorise that stock makes profit higher. The valuation itself must still follow the instructions and applicable syllabus treatment.
Frequently asked questions
What should an Okara family bring to an inventory discussion?
Bring the complete question, attempted valuation and the related cost-of-sales and profit calculations. Ask the student to explain where the closing figure is used. This helps a teacher distinguish the valuation decision from an arithmetic mistake or a missing link to another statement.
Why does higher closing inventory reduce cost of sales?
In the straightforward calculation, goods remaining at the period end are deducted from goods available for sale. A higher closing amount therefore leaves less cost attributed to goods sold. The learner should explain that relationship before stating the resulting effect on gross profit.
Does an inventory correction affect only profit?
No. Closing inventory is also an asset in the stated accounts, and the profit effect can change equity when other items are unchanged. Follow the figure through each relevant statement. Correcting one total while leaving dependent amounts unchanged can preserve an inconsistent answer.
Can an error affect the next period too?
Yes. Closing inventory becomes opening inventory in the next period in the simple sequence. An overstatement can therefore have an opposite profit effect next year if other relevant amounts are correct. Name the period before describing the direction, and do not treat two wrong annual results as harmless.
Where can families confirm current teaching support?
Contact Abeel Eschool admissions with the student's course details and a specific attempted question. Confirm availability and practical arrangements directly. Ask how the proposed task will check the unresolved valuation or linked-calculation decision in fresh independent work.
Ask about O and A Level courses
Share your subjects, current study stage and the support you need. The Abeel Eschool team can help you check the current course options.